We build software for banks, payment companies, wealth and insurance platforms — and for teams whose product happens to move money and now needs to survive an audit.
Double-entry ledgers, idempotent payment flows, reconciliation, KYC/AML orchestration and hardened operational tooling: the parts that quietly decide whether a fintech product scales or leaks.
Financial systems fail on edge cases: a duplicate webhook, a partial refund, a timezone boundary at month end. We model those states explicitly and prove the behaviour with reconciliation harnesses and property-based tests before launch.
Financial platforms we've built
Investment, payments and ledger projects documented in our case studies, each with security and compliance requirements built in.
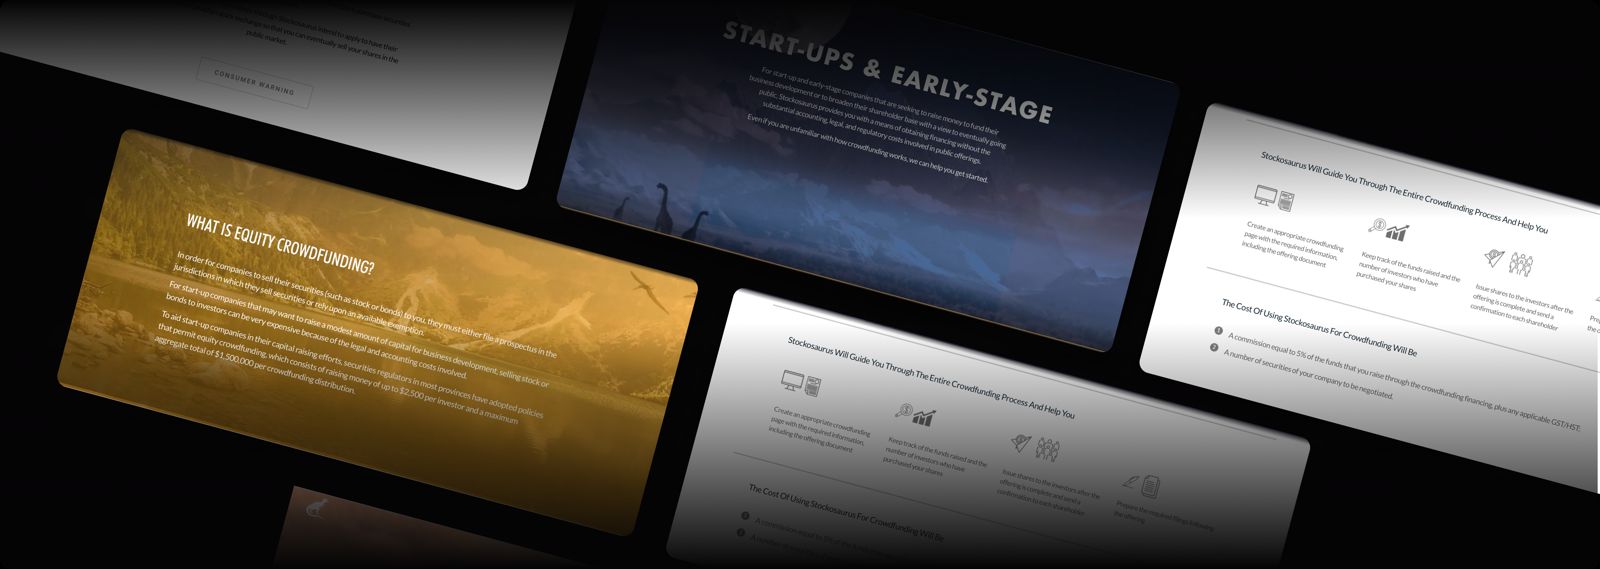
Equity crowdfunding platform for Canadian investors
A Canadian equity crowdfunding platform with investor registration, KYC identity verification, issuer pages and a secure backend for transactions.
Read the Stockosaurus case study →
Mobile and web platform for online gaming
Web and native mobile apps with secure payment gateways for deposits and withdrawals across multiple methods, plus backend systems for accounts and transactions.
Read the Arena Casino case study →
Blockchain supply chain platform
A blockchain supply chain platform with smart contracts, IoT data capture and an immutable transaction history that speeds up compliance audits.
Read the VeChain case study →Payments & ledgers
Double-entry ledger design, PSP integrations, payouts, reconciliation and dispute handling.
Onboarding, KYC & AML
Identity verification, screening, risk scoring and case-management workflows.
Customer & advisor platforms
Banking, wealth and insurance portals, plus internal operations consoles.
Trading & data interfaces
Low-latency dashboards, market data pipelines and reporting.
Digital assets
Custody integrations, on-chain settlement and smart-contract work where it genuinely adds value.
Risk & fraud tooling
Rules engines, ML scoring and analyst workbenches with full decision audit trails.
Typical financial services engagements
Embedded payments
Accepting, splitting and paying out money inside your existing product.
Ledger replacement
Migrating from spreadsheet-and-database accounting to an auditable ledger.
Compliant onboarding
KYC/KYB, sanctions screening and risk scoring with analyst review queues.
Operations consoles
Internal tooling for refunds, disputes, reconciliation and support with strict permissions.
Tokenised assets
Custody, settlement and reporting where on-chain infrastructure earns its place.
Fraud & risk scoring
Real-time rules and ML scoring with analyst workbenches and full audit trails.
Correctness first
Property-based tests and reconciliation harnesses prove the money maths, every release.
Audit-ready by construction
Immutable logs, segregation of duties and evidence your auditors can read.
Scope-reducing security
We architect card and PII flows to keep you out of the riskiest compliance scope.
Pragmatic on blockchain
We use it where it adds value and say so plainly when a database is the better answer.
Fintech-specific delivery experience
Teams who have shipped ledgers, PSP integrations and KYC flows before, not for the first time.
Load-tested for peak
Payment and trading systems proven under realistic peak-volume scenarios.
How to choose a fintech software development company
Financial software fails on edge cases and audits, not on happy paths. These questions help you compare any fintech software development company, including us.
Ask how they model money
Correct balances depend on design choices made early: a double-entry ledger, idempotent payment handling so duplicates can't double-charge, and reconciliation against provider statements. Ask the vendor to explain how they handle these, in plain language.
- How do you prevent a duplicate webhook from moving money twice?
- How do you reconcile our records against the bank or payment provider?
- How are partial refunds, chargebacks and reversals handled?
Plan compliance scope early: PCI DSS, KYC and AML
Card data, identity checks and anti-money-laundering screening each bring obligations. A good team designs the product to keep card data out of your systems where possible, and builds KYC and AML workflows around specialist verification and screening providers rather than reinventing them. Your compliance team and advisers stay in charge of policy; the software should make that policy enforceable and auditable.
Payment gateway integration is more than an API call
Taking a payment is the easy part. Payment gateway integration services also need to cover webhooks, retries, refunds, disputes, payouts, multiple providers and reporting. Ask how the vendor tests these flows before launch.
Banking and trading platforms need operations tooling
Behind every customer app sits an operations team handling refunds, disputes, reviews and support. Banking software development and trading platform development should include internal consoles with strict permissions and full audit logs, not just the customer-facing screens.
Agree audit evidence and ownership
Ask what documentation and evidence the vendor produces for audits and certifications, and make sure you own the code, infrastructure and data from day one.
- Banking
- Payments & fintech
- Wealth management
- Insurance
- Digital assets
- 01Money-flow modellingEvery flow, state and failure mode written down before implementation.
- 02Controls & architectureLedger, audit logging, segregation of duties and compliance requirements designed in.
- 03Build & proveProperty-based tests, reconciliation harnesses and load testing against peak scenarios.
- 04Launch & operateRunbooks, alerting, ops tooling and support for audits and certifications.
- 05Reconcile & monitorContinuous reconciliation and anomaly alerting once live.
- 06Scale & certifyCapacity growth alongside audits, certifications and new product lines.
What does a fintech software development company do?
It builds software that moves, records or manages money: payment integrations, ledgers, banking and investment platforms, onboarding with KYC and AML checks, and the operations tools behind them — designed for correctness, security and audits.
Do you build KYC and AML software?
Yes. We build onboarding, identity verification, screening, risk scoring and case-management workflows, integrating specialist verification and screening providers, with every decision logged for review.
Do you build banking software?
Yes. Customer portals, account and transaction views, internal operations consoles and ledger systems, working within your existing compliance program and change management.
Can you build a trading or investment platform?
Yes. We build trading and investment interfaces, market data pipelines and reporting — see our Stockosaurus equity crowdfunding case study for an example of investor onboarding and verification.
Do you still do blockchain?
Yes, as one tool inside financial infrastructure — custody, settlement, tokenised assets — not as a headline. If a database is the right answer, we'll say so.
Can you work under our compliance program?
We're used to working inside existing control frameworks, change management and external audit cycles.
Do you handle card data?
We design flows to minimise scope, and integrate PCI-compliant vaults and processors rather than storing card data where avoidable.
Can you integrate our existing PSPs and banks?
Yes — multi-PSP routing, bank file formats, Open Banking APIs and reconciliation across all of them.
How do you test money movement?
Property-based tests on ledger invariants, replay of production-like event streams and automated reconciliation against provider statements.
Do you support audits and certifications?
We produce the technical evidence, documentation and controls narrative your auditors and regulators ask for.
Related services and reading
- Cloud, DevOps & Platform EngineeringAudit-ready cloud infrastructure for financial workloads.
- AI Implementation & DevelopmentFraud, risk and document AI for financial operations.
- IT Staffing SolutionsEngineers with financial-services delivery experience.
- Blockchain Trends & Emerging Business Use Cases in 2025Where blockchain is finding real business use.
- AI Development Services in 2026: The Buyer's Guide Most Vendors Don't Want You to ReadHow to scope and buy AI development services.
Financial Services in production
Blockchain · DRM · Compliance
Blockchain · IoT · Web
Facial recognition · Biometrics · Security
Build financial software that passes review.
Describe the flows you need to support. We'll map the architecture, controls and delivery plan.